Eswatini Housing Fringe Benefit Valuation Changes: Practice Note IT/01/23 Now Effective 1 September 2026
Practice Note IT/01/23, issued under Legal Notice No. 4 of 2007 and sections 7(f) and (ff) of the Income Tax Order, revises the valuation rules for employer-provided accommodation and housing benefits in Eswatini. The previously announced implementation date of 1 July 2026 has been revoked, and the Practice Note will now take effect on 1 September 2026.
Legislative Summary of Changes
Valuation of Housing Fringe Benefits
A housing fringe benefit arises where an employer provides accommodation or housing to an employee, either free of charge or at a subsidised rate. The tax treatment depends on the ownership and use of the property.
For employer-owned accommodation, the taxable value must be calculated using the specific rental benefit values set out in Schedule A. Practice Note IT/01/23 updates the property classification criteria used for Schedule A valuations, which are now based on property condition and locality ratings.
Important: Implementation Date Revised to 1 September 2026
The originally scheduled implementation date of 1 July 2026 has been revoked. Practice Note IT/01/23 now takes effect on 1 September 2026. This deferral provides employers with additional time to prepare systems and recalculate housing benefit valuations based on the updated Schedule A rates.
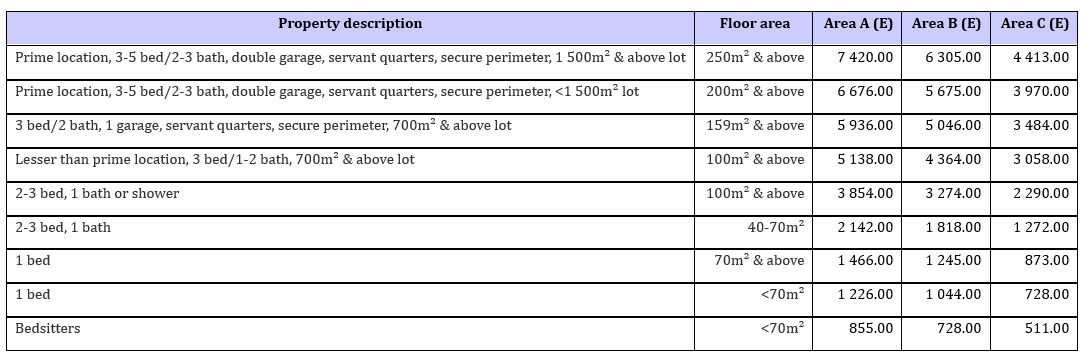
Schedule A Rental Benefit Values: Monthly Taxable Benefit (SZL)
The following table shows the updated Schedule A rental benefit values for employer-owned accommodation, categorised by property description and floor area, with values corresponding to different area classifications (A, B, and C):
Property Classification Criteria
Schedule A valuations are based on property classifications determined by two key factors: property condition and locality ratings. These criteria ensure that housing benefit valuations accurately reflect the quality and location of employer-provided accommodation, resulting in fair and consistent taxable benefit calculations across different employee groups and property types.
Effective Date and Application
The updated Schedule A valuation tables and property classification criteria are effective from 1 September 2026. All taxable housing fringe benefit calculations for employer-owned accommodation must use the new valuation basis from that date onwards.
Official Resources and Release Notes
- View the official publication of Practice Note IT/01/23.
- Refer to release note CM-18379, titled Calculation changes / Accommodation fringe benefit valuation for employer-owned accommodation (Schedule A) (1 of 2), for more information.